How Banks Create Money Out of Thin Air
Published: May 17, 2022
When a bank approves a loan, it can create a new deposit in the borrower’s account. The money appears alongside a promise to repay it. Our guide to types of money explains why that deposit is a debt the bank owes its customer.
That can sound like a trick. It helps to follow both sides of the transaction: what the borrower owes the bank and what the bank owes the borrower.
The bank as a place to store money
First, picture a bank that only stores money. Joe keeps physical cash. Maya deposits hers at the bank and uses a debit card to spend it.
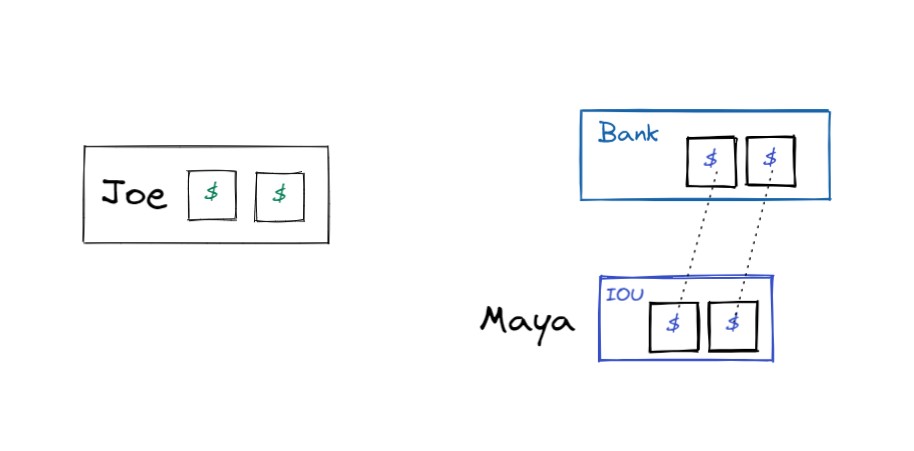
As more people deposit cash, the bank keeps a record of what it owes each customer.
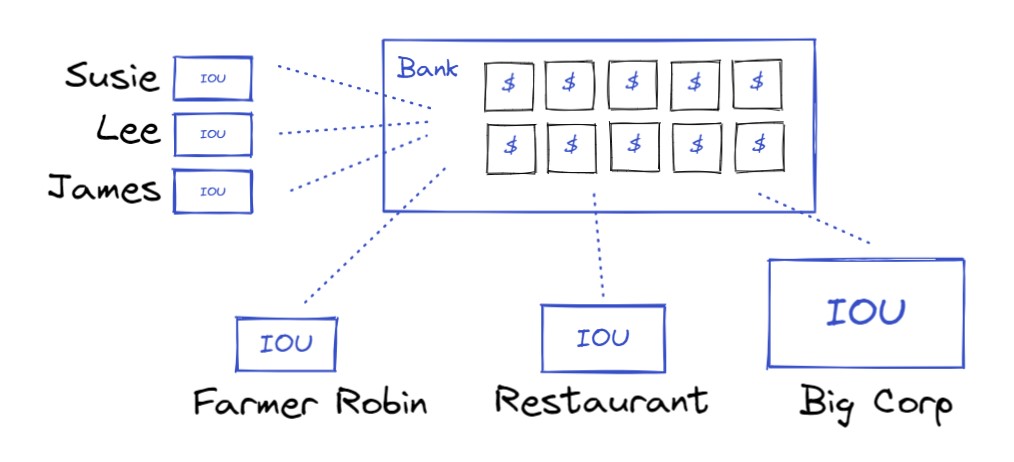
Customers can pay one another by transferring account balances. They don’t need to carry cash or make change.
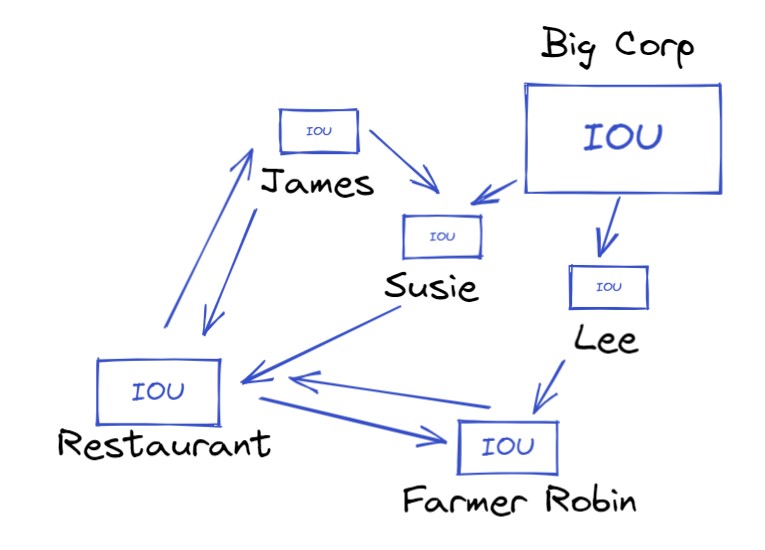
That picture makes banking look like storage and bookkeeping. Lending adds another job: banks also try to “turn money into more money.”
What changes when the bank makes a loan
When a bank makes a loan, it records the loan as an asset and creates a matching deposit for the borrower. It does not have to move another customer’s deposit into that account first. The Bank of England explains this process in detail.
Creating a deposit doesn’t let a bank lend without limits. It still needs capital, funding, and the ability to settle payments to other banks. It also needs borrowers who can repay.
Imagine James borrows $500,000 to buy a house. In this simplified example, he agrees to repay $600,000 over 30 years. The exact payments would depend on the loan’s interest rate and terms.
The bank records a $500,000 loan asset and a $500,000 deposit liability when it lends. Interest will be earned over time; the whole $600,000 of future payments is not profit on day one. The bank must cover funding costs, operating costs, and possible loan losses.
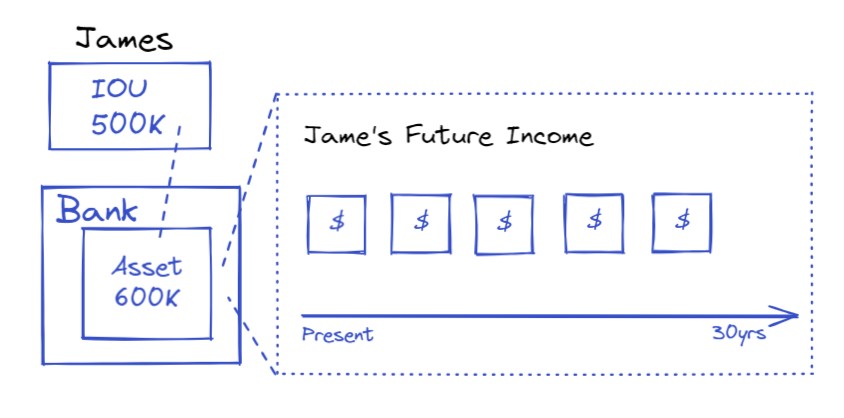
Other customers’ account balances haven’t been reduced to create James’s deposit. But if he pays someone at another bank, his bank must settle that payment.
Credit lets James spend now in exchange for payments later. The bank is taking a risk on his ability to keep that promise.
James pays the seller, who can use the money to pay fees, buy another home, or make other purchases. The loan has created spending power that can move through the economy.
More lending can support more spending. What the borrowed money is used for matters too.
James still owes the loan. His ability to spend today comes with payments that will shape his budget for years.
Borrowing can help someone buy equipment, training, or transport that increases their income. It can also pay for purchases that produce no future income.
A useful loan can help a borrower do something they could not afford to do yet.
Whether it works depends on both the lender judging the risk and the borrower being able to repay.
The 2008 financial crisis showed what can happen when lending incentives reward making loans without enough attention to repayment. Some lenders earned fees upfront while others carried the later losses.
Some borrowers also relied on rising house prices or accepted terms they did not fully understand. When prices fell, many owed more than their homes were worth and struggled to keep making payments.
Why a loan affects more than the borrower
In 2013, Ray Dalio estimated about $50 trillion in US credit compared with $3 trillion in money. Those are historical figures using his definitions, not current totals.
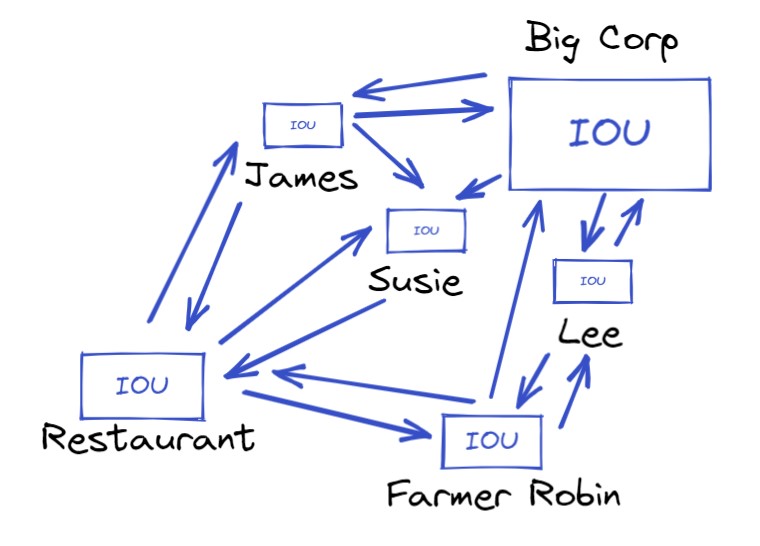
Credit supports purchases that become someone else’s income: a restaurant’s sales, a contractor’s invoice, or an employee’s paycheck.
Those arrangements depend on future payments arriving. When borrowers cannot pay, lenders and the people relying on them can take losses.
Wars, natural disasters, and pandemics can interrupt that chain. Lost income makes debts harder to repay, and worried lenders may cut back on new loans just when borrowers need cash.
Companies borrow against expected future income too. When financing is affordable, they can fund expansion. When lenders become less confident, borrowing can cost more or become harder to obtain.
That matters especially for companies whose expected profits are many years away. A change in financing costs or confidence can change what investors will pay for their future earnings .