How to 'Safely' Gamble
Published: March 14, 2022
Suppose you bet $100 on a fair double-or-nothing game. Half the time you gain $100; half the time you lose it. The expected profit is zero: 0.5 × $100 − 0.5 × $100 = $0.
Now give yourself a 60% chance of winning and a 40% chance of losing. The expected profit becomes $20 per $100 bet: 0.6 × $100 − 0.4 × $100 = $20. You have an advantage. You can still lose your money.
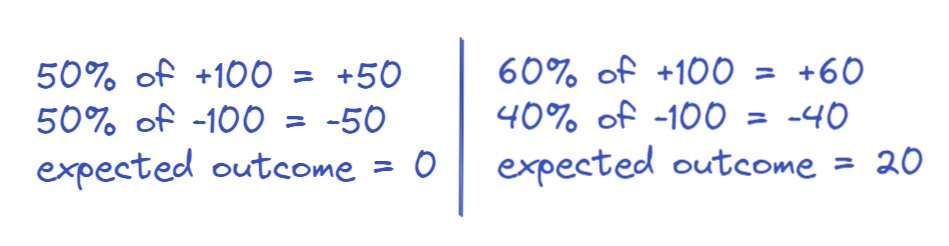
Bet everything and one loss ends the game. The size of your bet determines whether you can stay around long enough to benefit from favorable odds.
Try the Theory A Kelly game . Change how much you bet each round and watch what happens to your balance.
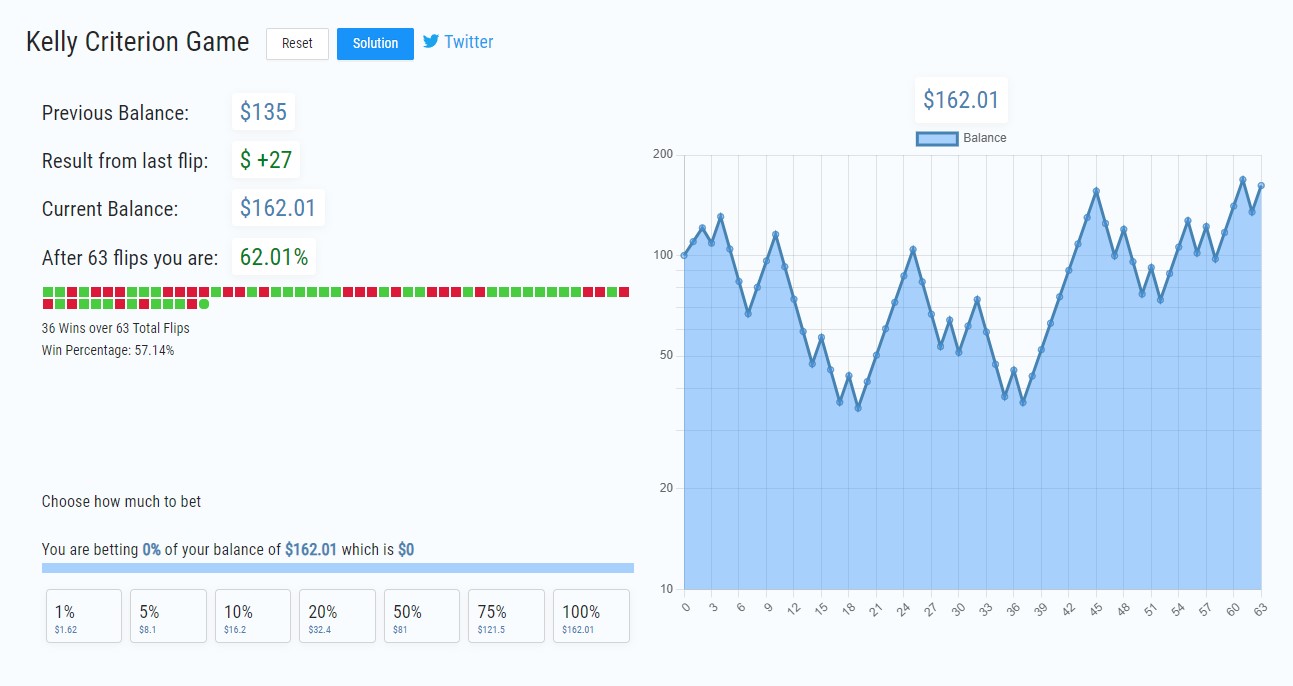
Two ideas explain what you’ll see: the Kelly Criterion and gambler’s ruin.
The Kelly Criterion
The Kelly Criterion calculates a bet size that maximizes expected long-run logarithmic growth, given known probabilities and payoffs. It aims for growth over repeated bets; it does not promise a smooth ride.
Bet too much and losses can overwhelm your advantage. Bet very little and you use less of the opportunity .
In a game, the same odds can be available every round. In markets, an opportunity can disappear as people trade it . That makes both the size of a trade and the time available matter.
Kris Abdelmessih describes that limit in his article on trade sizing :
The bigger you attempt to trade at edgy prices, the more information you leak into the market. You are outsizing the available liquidity by allowing competitors to reverse engineer your thinking.
In our game , each bet has a 60% chance of doubling the amount wagered. The Kelly calculation gives 20% of the current bankroll per round. That can feel like a lot because it is a volatile strategy.
The run below turned $100 into $1,374, but along the way the balance fell from $200 to $50. That is a 75% loss in a game with favorable odds.
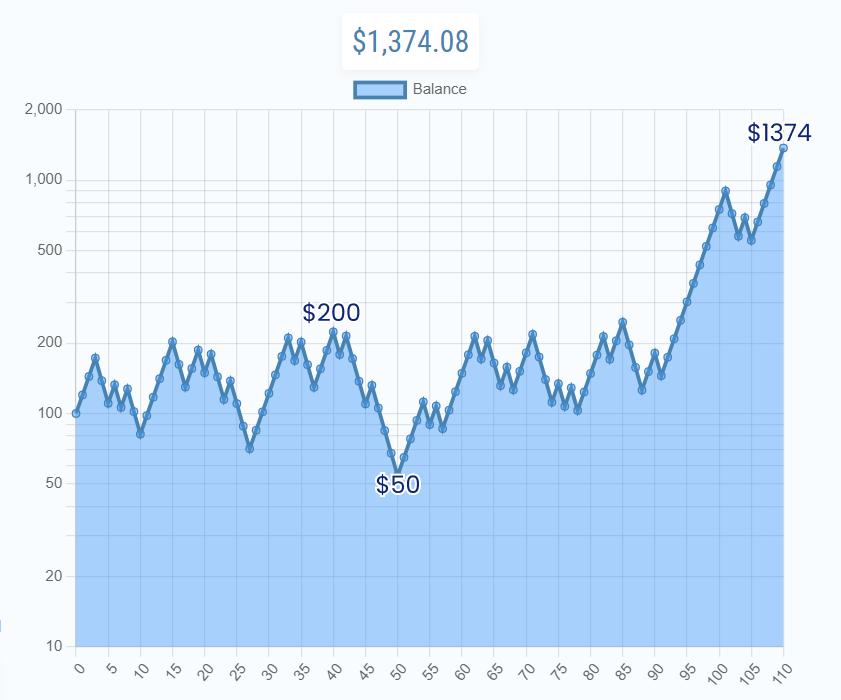
With a million-dollar starting balance, a 75% loss would mean losing $750,000. Could you keep following the strategy? In the game, the win probability is programmed in. In an investment, your estimate could be wrong.
One response is fractional Kelly: bet a fraction of the amount the formula suggests.
If the calculation suggests 20%, half Kelly means betting 10%. That reduces exposure to a losing streak and to errors in your estimated odds. It still leaves you exposed to losses.
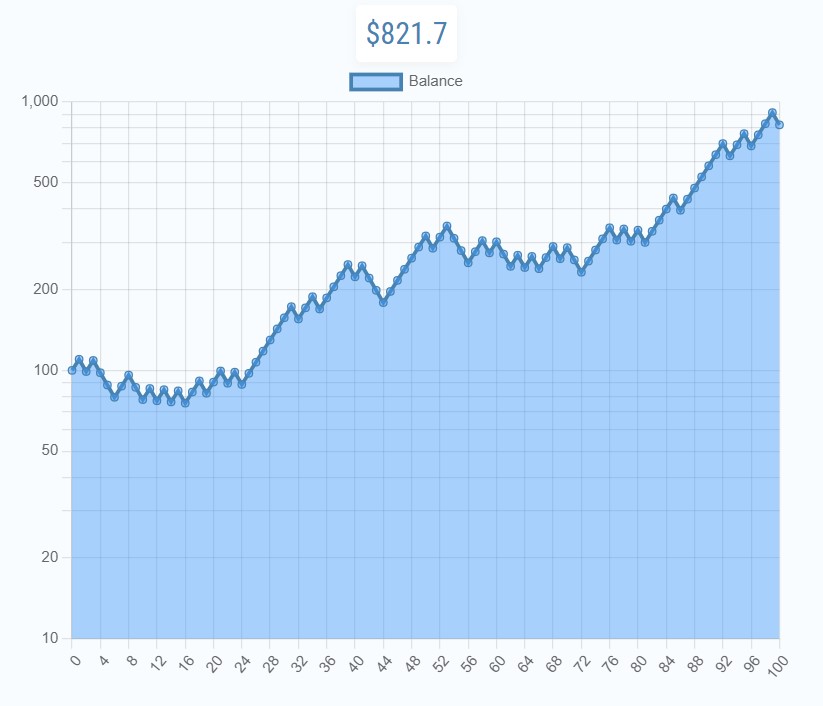
This run bets 10% each round. Its ending balance is lower than the earlier example, but its path is easier to stomach. Individual runs can differ.
Gambler’s Ruin
Gambler’s Ruin is stated:
A persistent gambler who raises his or her bet to a fixed fraction of the gambler's bankroll after a win, but does not reduce it after a loss, will eventually and inevitably go broke, even if each bet has a positive expected value.
Bet your whole balance every round and the first loss wipes you out, even with a 60% chance of winning each bet.
Betting 50% or 75% of your remaining balance can also drive it toward zero in this game over repeated rounds. A few spectacular wins can hide the damage from consistently betting too much. Try those settings in the simulator.
In the run below, a lucky streak takes $100 to $46,000. Continued large bets eventually leave less than a dollar.
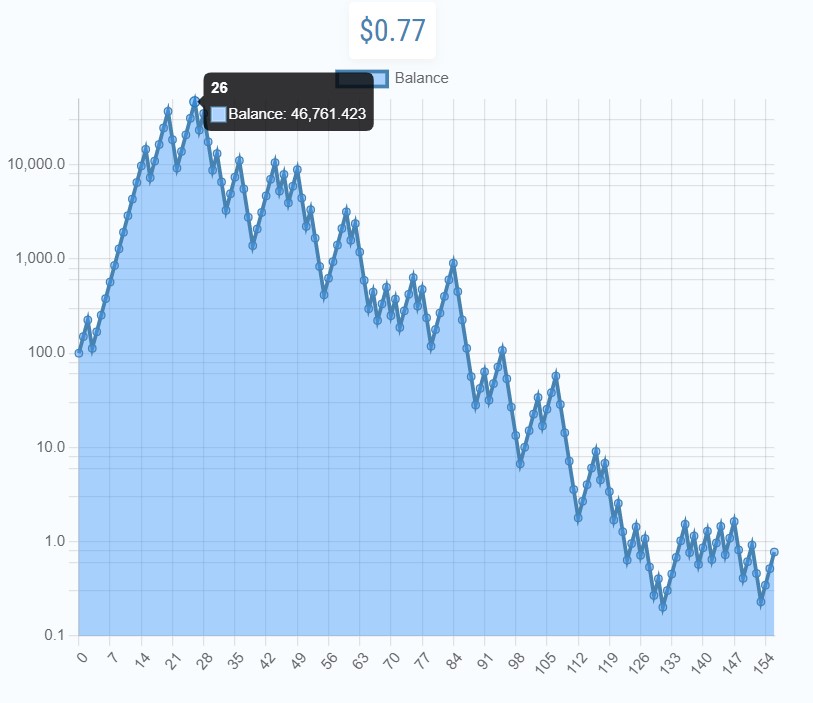
The odds in this game are known and favorable. In real trading, including the bets shared on r/wallstreetbets , the odds themselves are uncertain. A dramatic winning screenshot says little about whether the strategy can survive repeated losses.
For money to compound over many years, there must be money left to invest after a bad period. A bet that threatens that ability needs more scrutiny than its possible payoff alone suggests.
Leave room to be wrong
The simulator makes the tradeoff visible. Larger bets can grow a balance quickly and make losses much harder to recover from.
Real investments do not come with known probabilities. Kelly can help you think about sizing, but its answer is only as sound as the odds and payoffs you put into it.
Our valuation guide looks at what a business might earn. Position sizing asks how much of your money should depend on that estimate. Both questions belong in investment research .